This post reports a backtest of a systematic 1-hour strategy on a panel of EUR-quoted equities. The run parameters and headline result metrics are shown below.
\n\n\n\nThis is a historical backtest, published for informational and educational purposes only , not financial advice, not a recommendation, and not a trading signal. We would not trade it as-is: it is research only. Past performance is not indicative of future results.
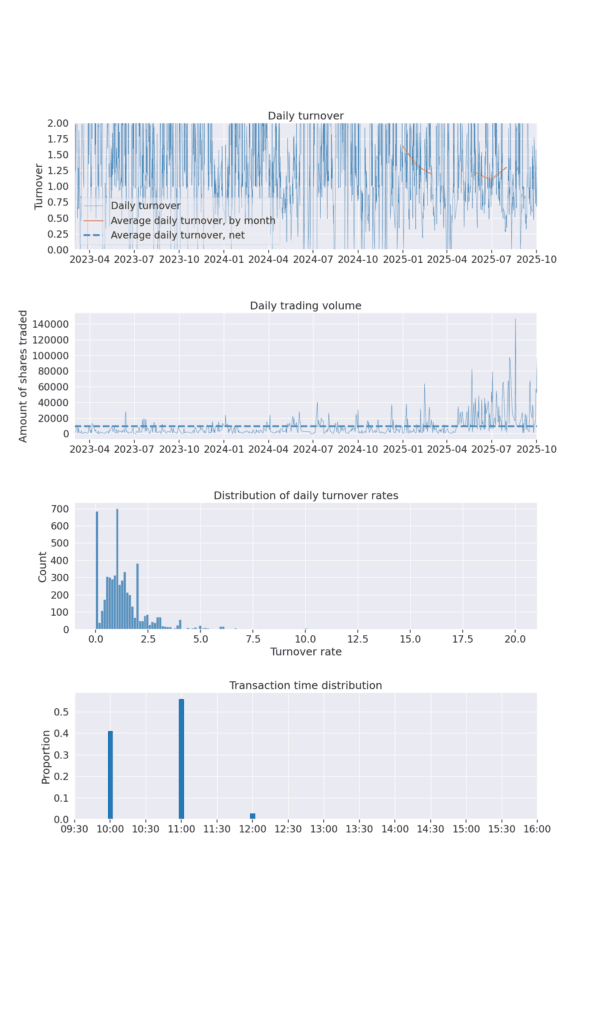
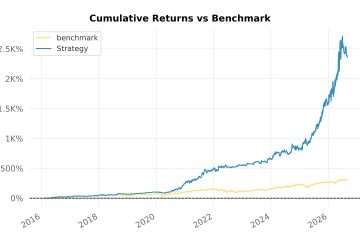
\n\n\n\n\nThis is one of the systematic strategy backtests we run and publish as research.\nIt uses a 1-hour timeframe on a panel of EUR-quoted stocks.\n\ndate_start_simulation: 2023-03-01 00:00:00+00:00\ndate_start: 2023-01-06 00:00:00+00:00\ndate_end: 2025-10-03 00:00:00+00:00\nbase_currency: EUR\ninitial_cash: 100000.0\nposition_target_w: 0.1\nposition_target_hard_limit: 10000000.0\nbar_size: 1 hour\nnbar_back_for_stop: 0\ntrailing_stop: 17.0\nstop_limit: False\nnbar_freeze: 2\nenable_freeze_global: False\nposition_max_w: 0.25\nmax_new_position_per_bar: 3\nnb_symbol: 1029\n\nWallet final : value=437862 return_arr=55.00% maxdd=19.66% ulcer=4.44% exposure=32.90% return=337.86% nbtransaction=1311 winrate=44.70% sharpe=1.72 sortino=4.02 calmar=2.54 stability=0.641 k=102.89 composite=7.591306 rr=3.54 nbrow=0 cash=437862 return_mean=2.15 return_max=589.36 return_min=-23.12
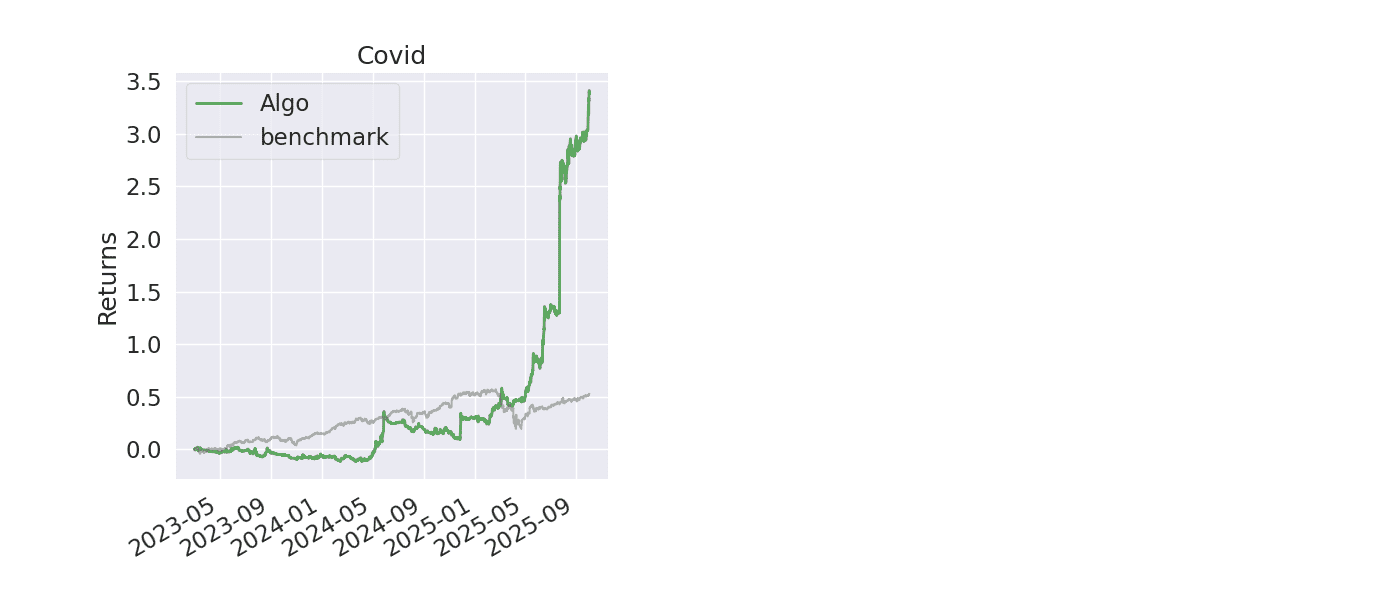
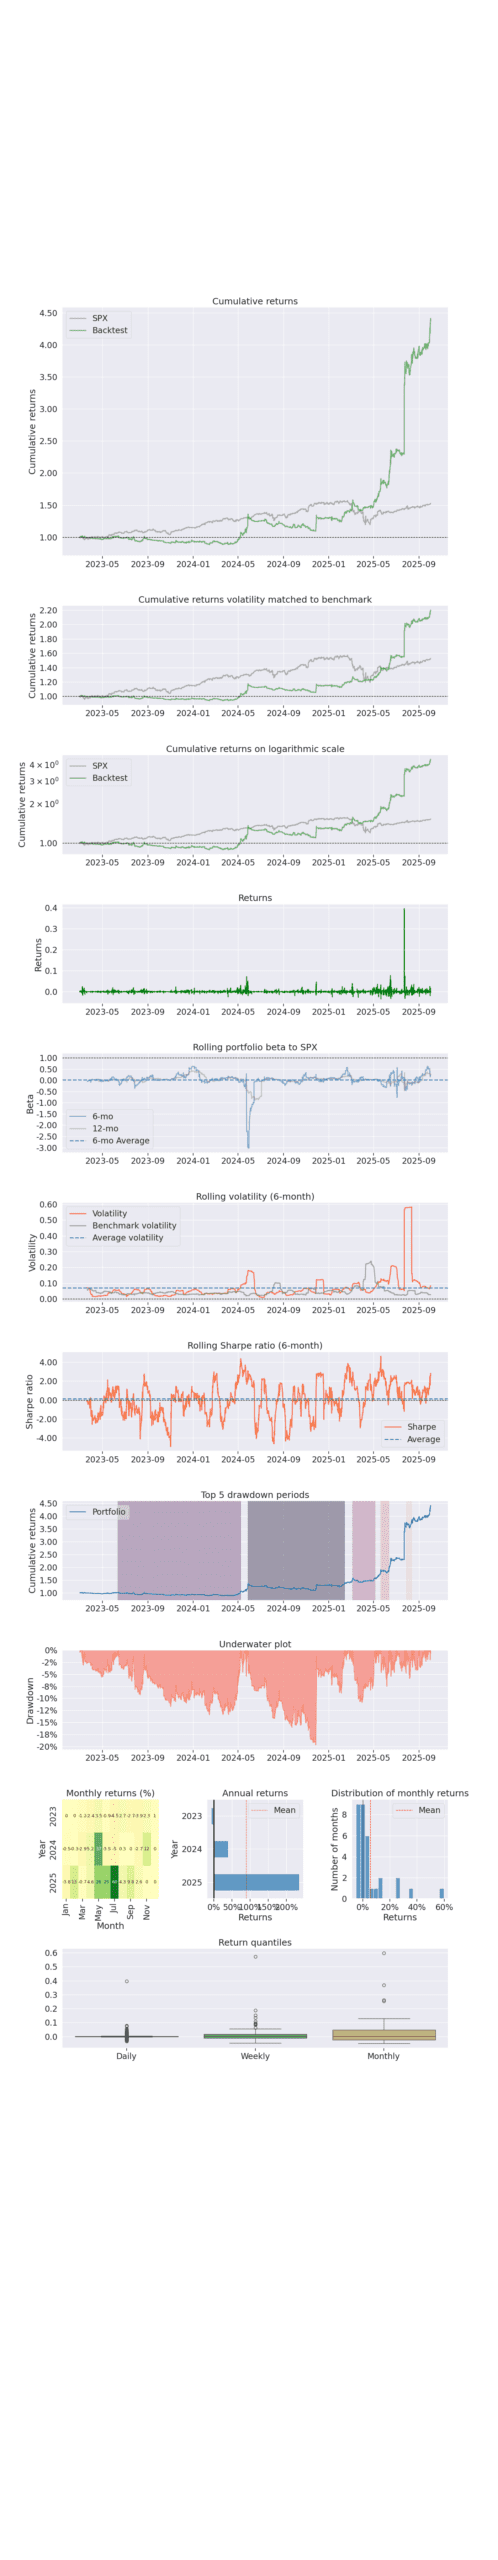
Out-of-sample cutoff. This strategy’s rules and parameters were frozen on 3 July 2025. All performance shown after that date is genuine out-of-sample / forward-tracked data , it post-dates the freeze, so no hindsight or selection could have shaped the rules.
\n\n\n\n\nFrequently asked questions
\n\n\n\nWhat universe and timeframe does Backtest 85 cover?
\n\n\n\nIt runs a systematic strategy on a panel of 1,029 EUR quoted equities using 1 hour bars. The simulation compounds from 1 March 2023 to 3 October 2025, starting from 100,000 EUR of capital.
\n\n\n\nWhat were the headline results?
\n\n\n\nThe run returned 337.9% cumulatively, an annualized 55.0%, against a maximum drawdown of 19.7%. Sharpe was 1.72 and Sortino 4.02 over 1,311 transactions with a 44.7% win rate. The return figure only means something read next to the drawdown.
\n\n\n\nHow much of the period is out of sample?
\n\n\n\nThe rules and parameters were frozen on 3 July 2025. Everything after that date post-dates the freeze, so no hindsight or selection could have shaped the rules. The window before it is in sample and should be discounted accordingly.
\n\n\n\nIs the strategy invested all the time?
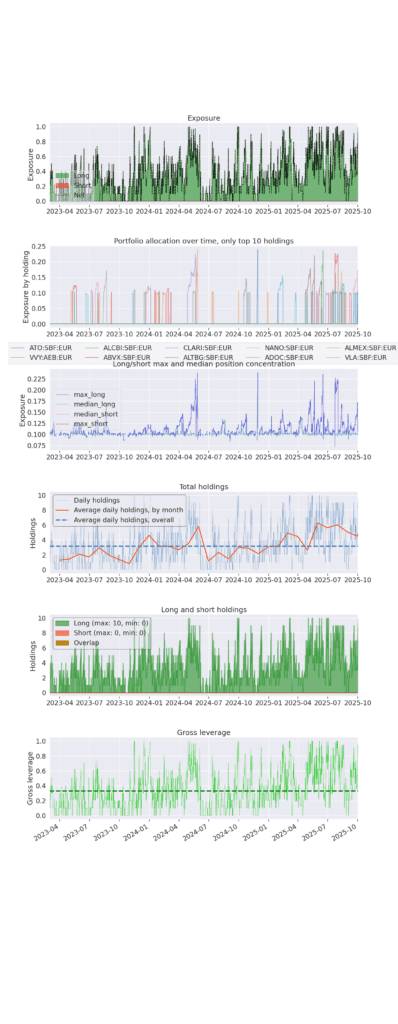
\n\n\n\nNo. Average net exposure is 32.9%, so the book sits in cash for most of the window. The exposure chart shows long only positioning with no short side.
\n\n\n\nIs this a trading signal I can act on?
\n\n\n\nNo. This is a historical backtest published as research and education. It is not financial advice, not a recommendation and not a signal to trade. We would not trade it as-is: it is research only. Past performance is not indicative of future results.
\n\n\n\n\n\n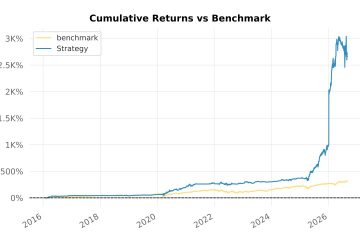
0 Comments